Rethinking the Banking Customer Journey
September 21, 2026
September 21, 2026
Digital banking continues to shape how customers interact with financial institutions. According to the American Bankers Association’s 2025 Preferred Banking Methods survey, 54% of U.S. consumers most often use a mobile app to manage their bank accounts, while 95% rate their bank’s online and mobile experience as excellent, very good, or good.
Those numbers demonstrate how firmly digital banking has become part of the customer experience. However, they do not mean every banking interaction begins and ends within an app. Customers still move between digital tools, appointments, branches, specialists, and other forms of assistance depending on the service they need.
That connection between customer journeys and the operational workflows supporting them was a recurring theme for ACF Technologies at FinovateFall 2026 in New York. Conversations across banking, financial services, and FinTech pointed toward a larger opportunity: creating modern workflows that connect customer-facing convenience with the operations required to deliver it.
Modernization was at the center of many conversations, but not simply in the context of adding another digital channel. Interest centered on how financial institutions can better align customer journeys with scheduling, service availability, operational workflows, reporting, and the teams delivering service.
Appointment management was one area of particular interest, including greater control over availability, appointment limits, and cancellations. Reporting and AI-supported operational insights generated interest as well. Perhaps most notably, those conversations extended beyond traditional banking organizations. FinTech companies were also exploring how customer journey technology could complement the solutions and relationships they already bring to financial institutions.
That broader interest suggests an important shift. The next phase of financial services technology may depend increasingly on how well different systems, channels, and operational processes work together.
AI can support that shift by helping financial institutions turn the operational information generated throughout the customer journey into more useful insight:
ACF's Neuro AI capabilities, for example, are designed to analyze service interactions for trends, anomalies, demand patterns, and operational inefficiencies. These insights can complement traditional reporting and help organizations better understand what is happening throughout their service environments.
Connecting digital and in-person banking helps financial institutions create greater continuity across the customer journey. When scheduling, service availability, workflows, and operational insights work together, teams can better support customers as they move between channels and services.
One of the most interesting takeaways from FinovateFall was the level of engagement from FinTech organizations.
FinTech providers already support critical areas of the financial ecosystem, including risk, payments, analytics, identity, communications, and digital banking. Customer journey technology can serve a different but complementary purpose by helping financial institutions manage how customers move between services, channels, employees, and physical locations.
This creates an opportunity to look at the financial technology ecosystem more broadly. Rather than expecting one platform to perform every function, financial institutions can focus on how specialized technologies work together to create a more connected operating environment.
For FinTech providers, customer journey orchestration can add another dimension to conversations with banking customers. A solution may address one important part of the customer relationship, while technologies supporting appointment management, customer flow, workflows, and operational intelligence help connect that capability to the larger service experience.
For financial institutions, this type of connected approach can help reduce the operational silos that emerge as technology environments expand.
FinovateFall 2026 reinforced that banking modernization is not simply about introducing another digital tool. The larger opportunity is connecting customer-facing technology with the workflows, people, information, and operational decisions required to support the complete journey. As customer expectations continue to evolve, financial institutions need visibility not only into how customers choose to engage, but also into how effectively their operations support those choices.
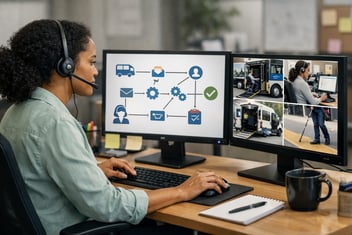
ACF Technologies uses the Q-Flow platform to bring appointment scheduling, customer flow, interaction management, and business process orchestration together within a unified environment, helping organizations connect more of the customer journey while improving visibility behind the scenes. For banks, financial institutions, and the FinTech companies supporting them, that connected approach can help turn individual service interactions into a more cohesive customer experience.
The future is now, and it begins with smarter decisions.